Plan while the sky is clear. That is the only time it works.
Asset protection is not a product you buy after something goes wrong. It is a structure you put in place while nothing is wrong, and it is one of the main reasons families come to us with something real to protect.
A lifetime of work, held in a single name, with nothing between it and a bad day
The problem
Most families' assets are exposed by default. The house, the accounts, the rental property and the business interest are all held individually, and a single lawsuit, a single accident, or a single long illness reaches all of it at once.
The other exposure is generational. Money left outright to a child is money exposed to that child's divorce, that child's creditors, and that child's judgment at twenty-three. Parents are often protecting against the first risk and have never been told about the second.
Everything held in individual name, with no structure at all
A business and a personal estate that are indistinguishable
An inheritance that would land outright in a child's marriage
The cost of long-term care, which quietly outruns most plans
How we help
Structure, put in place early, and reviewed as the risks change
Real asset protection is layered. It starts with getting the right things in the right entities and the right names, continues through the trust structures that hold what you leave behind, and includes the unglamorous work of making sure your insurance and your titling are not quietly undoing each other.
It also has a hard timing rule, and we will be blunt about it on the first call: planning done in the face of a known claim is a different and far weaker thing than planning done in advance. The families who get real protection are the ones who started early.
What it does for your family
What this actually changes
Read what changes 4
What you leave is harder to lose
A properly drafted protective trust can keep an inheritance out of a divorce settlement and away from a beneficiary's creditors, while still being available for their benefit.
Your business risk stops at the business
Getting the entity, the titling and the insurance aligned keeps a commercial problem from becoming a family one.
Care costs stop being an open-ended hole
Planning for long-term care in advance is the difference between spending down an estate and preserving it. That is what our Elder Protection Plan is for.
Everything is coordinated
Protection fails at the seams. We work alongside your advisors so the estate plan, the entities and the insurance are one plan.
Plan while the sky is clear. That is the only time it works.
Asset Protection at Estate Planners for Life
What families build
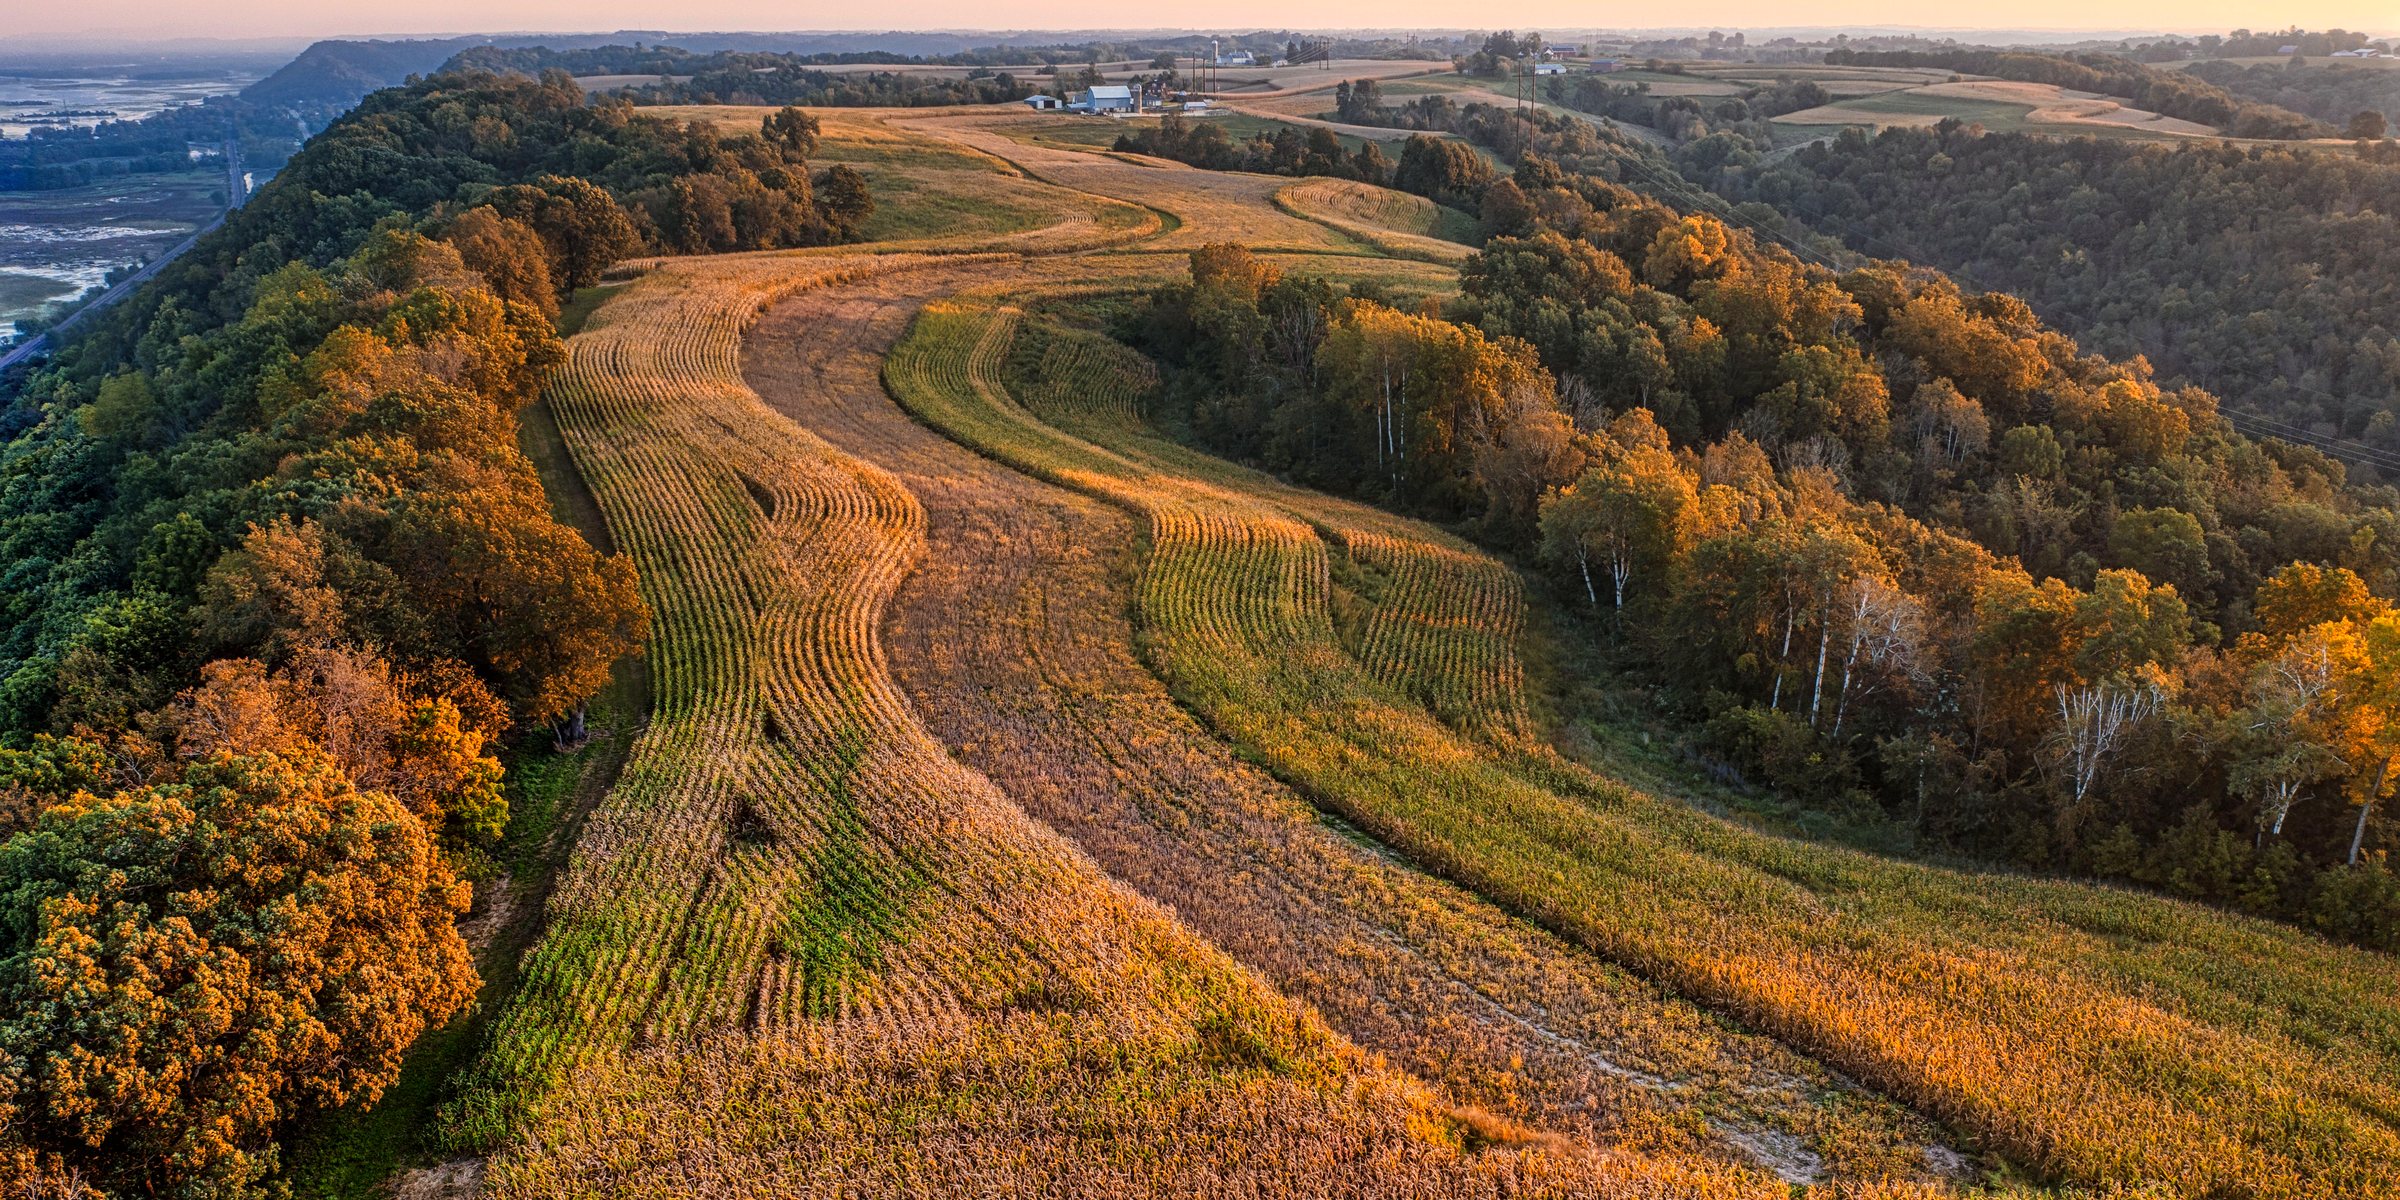
What Oklahoma families work to protect
Farm and ranch land, mineral interests, a family business, a home. Asset protection is about keeping what a lifetime of work built in the family, and out of reach of the risks that can take it.
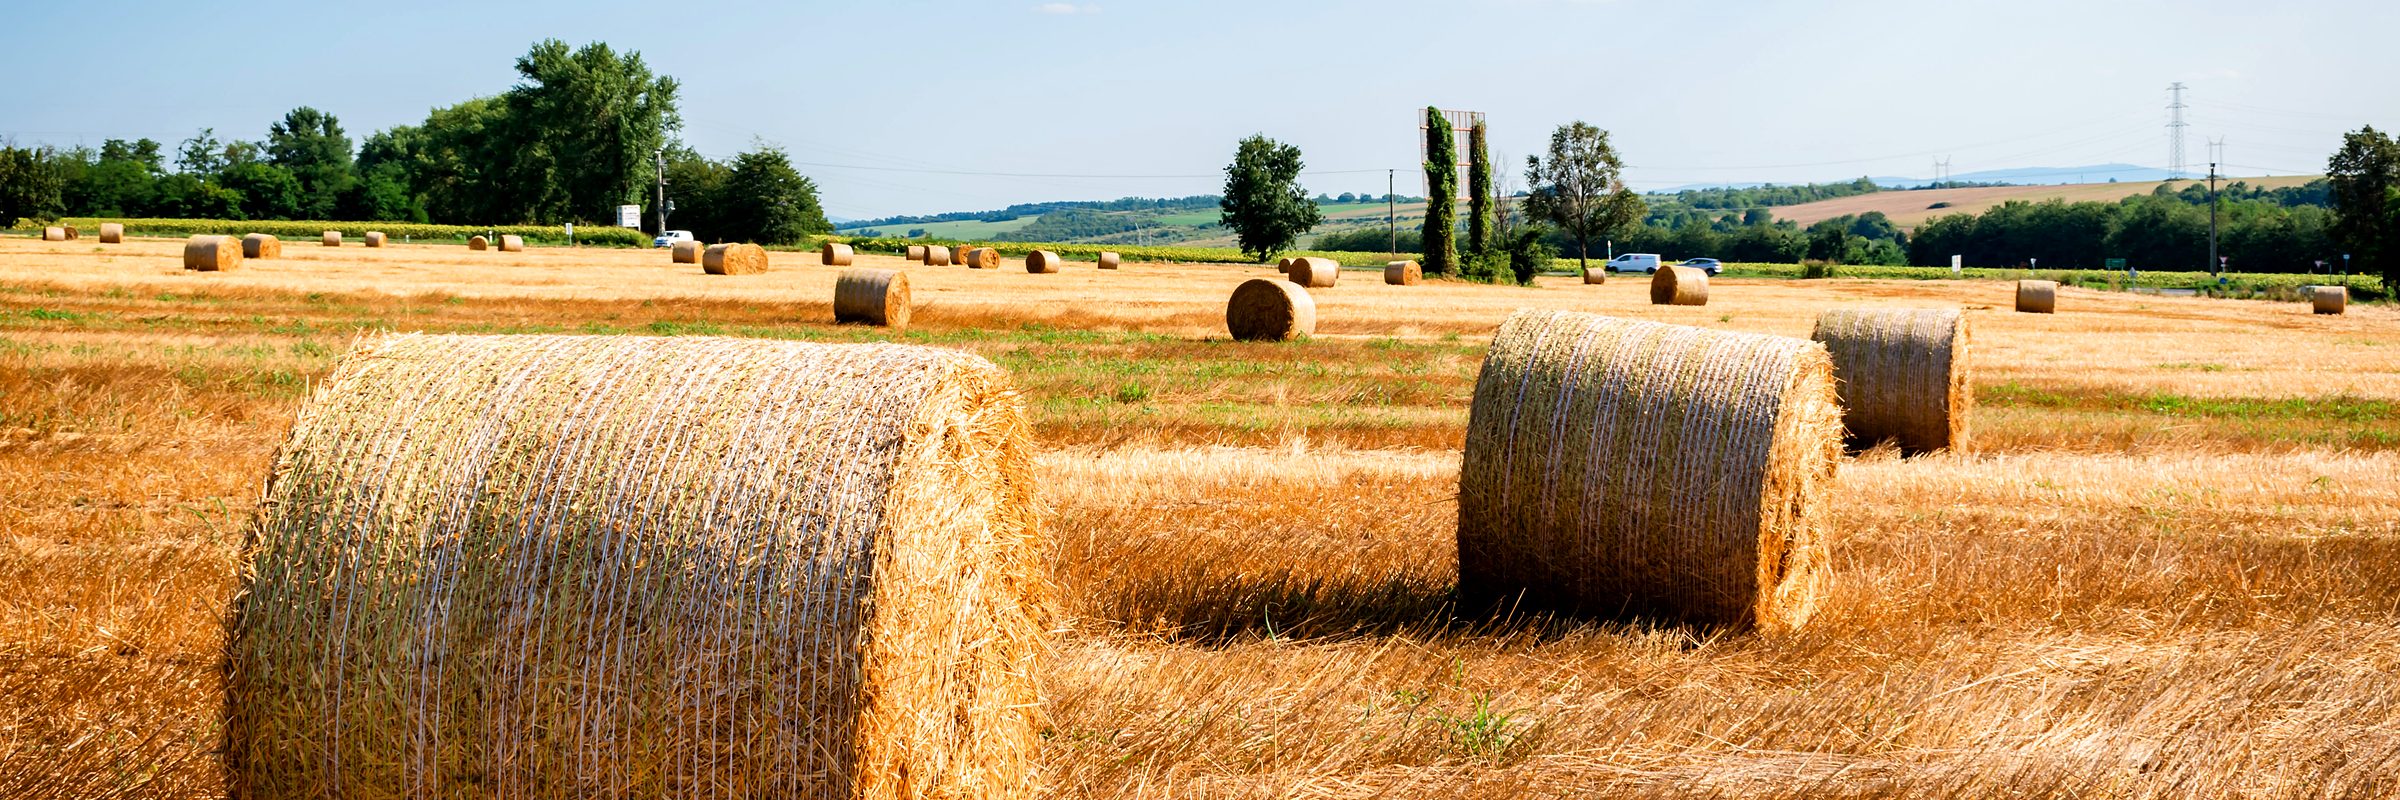
Oklahoma land, farms and fields, and the families who plan for them
Who this is for
This is probably right for you if you can check a few of these boxes…
own a business, a farm or rental property
have significant investments or retirement assets
practice in a profession with real liability exposure
want an inheritance protected from a child's divorce or creditors
are worried about the cost of long-term care
own land, minerals or property in more than one state
And when it is not. Asset protection is not a way to escape a debt you already owe or a claim already on the horizon. Planning at that point can be undone, and we will not put a family in that position. This is planning for the sky-is-clear season.
Situations we see often. They are written as patterns, not as anyone’s story.
Read the situations 4
A business owner with everything in one basket
An owner who has built a real company often has the company, the building it sits in, the equipment and the family home all connected by little more than habit. Separating the operating business from the real estate, getting the titling right, and coordinating that with the estate plan is ordinary, unexciting work that changes the entire risk profile of the family.
Parents worried about a child's marriage
Nobody wants to say out loud that they are planning around their son-in-law. It is one of the most common reasons families ask about trusts, and it does not have to be adversarial. An inheritance held in a protective trust for a child is still theirs to benefit from, it is simply harder for a divorce court or a creditor to reach. Most children, once it is explained, are relieved rather than offended.
A family facing the cost of care
Long-term care is the risk that undoes more Oklahoma estates than lawsuits ever will. Planning early, before care is needed, opens options that simply are not available once someone is already in a facility. This is the work behind our Elder Protection Plan, and the earlier the conversation, the more there is to work with.
Landowners with minerals
Agricultural ground and mineral interests carry their own risks: liability from the operation, fractionalisation among heirs, and the difficulty of ever selling or leasing anything once an interest has divided across three generations. Structure put in place now is what keeps a family able to make a decision together in twenty years.
Oklahoma considerations
Asset protection, in Oklahoma terms
Read the Oklahoma detail 5
Oklahoma gives families more to work with than many realize, and also more to be careful about. Homestead treatment, the way property is titled between spouses, and the entity choices available for a farm or a business all matter, and they interact with the estate plan rather than sitting beside it.
The distinctly Oklahoma piece is land and minerals. An interest that seemed small a generation ago has often divided among cousins who have never met, and every one of them has to sign. Planning that anticipates it, through trusts and entities that hold the interest as a whole, is worth more than any document drafted after the fact.
Homestead and how the family residence is treated
Titling between spouses, and what it does and does not protect
Entity choice for a farm, ranch or operating business
Mineral and royalty interests, and keeping them from fractionalising
Long-term-care exposure, planned for well in advance
What happens next
The Estate Planners for Life™ process
People want to know what they are walking into. Here is the whole shape of it, from the first conversation to the day your family needs the plan to work.
01
Planning
Discovery, which starts with the Right Fit Call
Strategic recommendations for your circumstances
Document design
Review, in plain language, until it is clear
Signing
Funding, for trust-based plans
02
Maintenance
An annual check in
A periodic review of the plan, updated as needed
We are here when laws change or when life presents a change
03
Administration
Trust execution and administration when someone passes
We help you put the plan to work when it is needed most
Questions Oklahoma families ask about asset protection
Plain answers, at the length the question deserves. If yours is not here, a Right Fit Call answers most questions for your family specifically.
What is asset protection planning?
It is arranging how you own things, and how your beneficiaries will own what you leave them, so that ordinary risks like a lawsuit, a divorce or the cost of care do not reach everything at once.
Is this only for wealthy families?
No. The families with the most to lose in proportional terms are usually the ones who built something modest and have no structure around it at all.
Can I protect assets after I have been sued?
Not meaningfully, and attempting it can make matters worse. Transfers made in the face of a known claim can be unwound. This is planning that has to be done in advance.
Does a revocable living trust protect my assets from my creditors?
During your lifetime, generally not, because you retain control of it. Its protective power is mostly for your beneficiaries after you are gone.
How do I protect an inheritance from my child's divorce?
By leaving it in a properly drafted trust for their benefit rather than outright. That is one of the most common and most effective things a family plan does.
What about the cost of a nursing home?
Long-term care is planned for as its own category, and the options narrow considerably once care has already begun. Our Elder Protection Plan exists for exactly this.
Is an LLC enough on its own?
An entity is one layer. It works when it is respected, funded, insured and coordinated with the estate plan, and it fails when it is a name on a filing and nothing else.
Will asset protection affect my taxes?
Some structures have tax consequences and some have none. We work with your CPA rather than guessing, and we will tell you when a structure is not worth its cost.
Can I still use my own money?
In most family planning, yes. Protection is largely about what your beneficiaries receive and how it is held, not about restricting your own life.
Does this protect against everything?
No, and anyone who says otherwise is selling something. It reduces exposure. It does not make anyone judgment-proof, and we will be straight with you about where the limits are.
How does this fit with my insurance?
Insurance is the first layer and structure is the second. We look at both, because families are often underinsured in one place and over-structured in another.
When should I start?
Before you think you need to. The value of this work is almost entirely a function of how early it was done.
Do you work with my financial advisor and CPA?
Yes, and we prefer it. Plans fail at the seams between professionals, so we would rather be in the room.
Estate planning is a process, not an event. Start with a Right Fit Call: a short, no-pressure conversation to see whether we are the right firm for your family, and what a plan that walks alongside you would look like.